
Lihat juga


 05.10.2026 07:51 AM
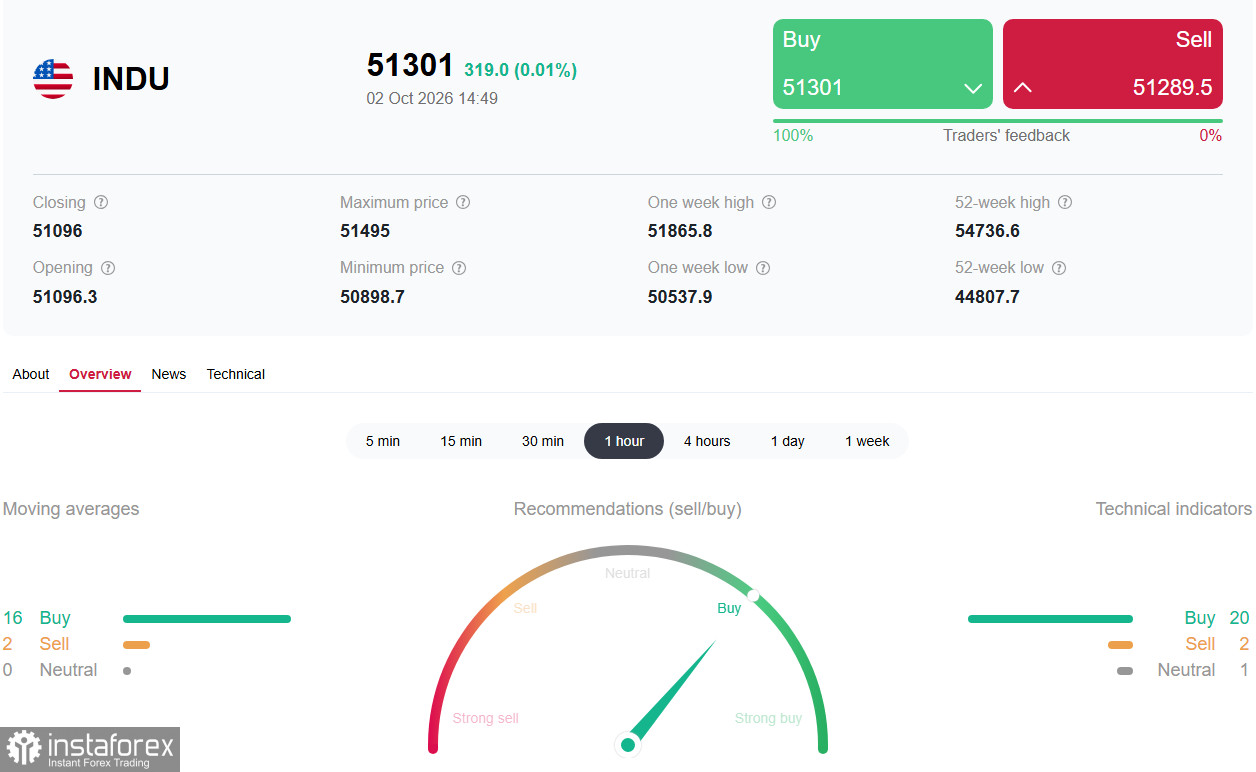
*see also: InstaTrade trading indicators for DJIA (INDU)
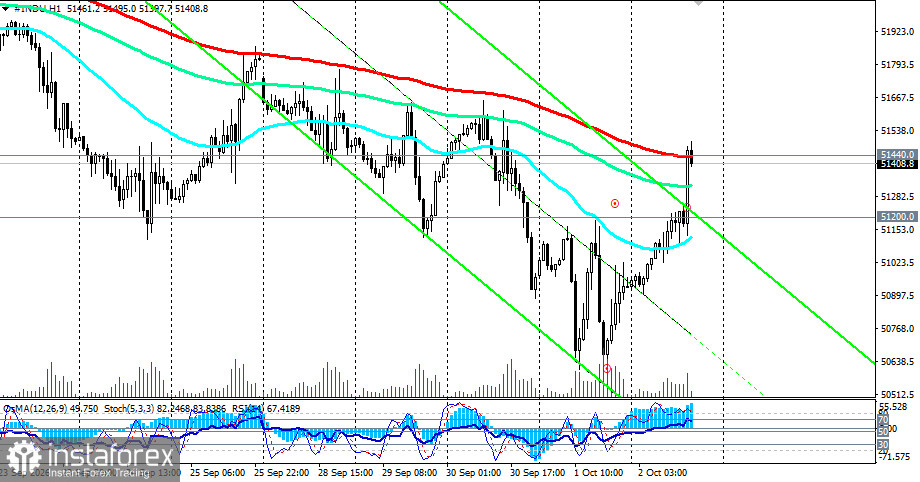
The Dow Jones Industrial Average (DJIA) is trading around 51,380.0 at the time of this report after a sharp rebound triggered by the US nonfarm payrolls release. The data came in markedly weaker than expected, shifting the market dynamic: the odds of an October Fed rate hike plunged, and equities received a welcome respite. The key question is whether this marks the start of a sustainable reversal or only a temporary bounce within a downtrend.
New payrolls collapsed to 29,000, well below the consensus forecast of 90,000 and the revised August print of 133,000 (initially reported as 162,000). Moreover, July was revised from +21,000 to -10,000. The cumulative two-month revision totaled -60,000.
The unemployment rate rose to 4.2% versus expectations of 4.1%. The participation rate increased to 61.8% from 61.6%. Average hourly earnings rose only 0.1% month-on-month, and the annual rate slowed to 3.0%, below the 3.2% forecast.
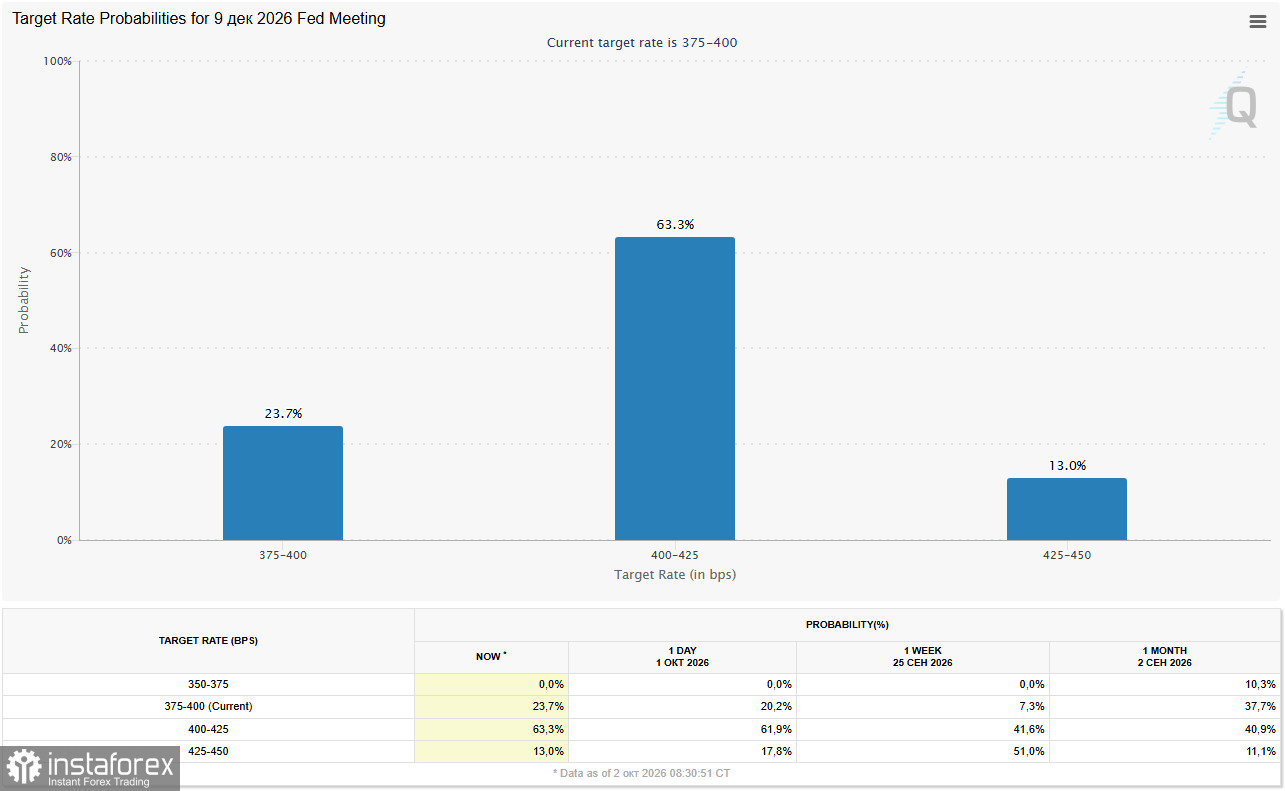
The market immediately repriced interest rate odds. According to CME FedWatch, the probability of an October Fed hike fell from 64% a week earlier to 17% after the NFP release. However, a December hike still looks likely (75–80%) — the market hasn't abandoned the idea of further tightening; it has merely pushed it later.
On Wednesday, October 7, at 18:00 GMT, the FOMC minutes will be released. After the weak NFP print, the market will look for confirmation that the Fed is prepared to pause in October. If the minutes show some committee members advocating a pause, that would bolster equities.
On Wednesday, October 14, at 12:30 GMT, the US Consumer Price Index (CPI) for September will be released. This is the next major release that will determine whether the market keeps pricing in a December hike. If inflation proves soft, the DJIA would receive additional support.
On Thursday, October 15, at 12:30 GMT, US retail sales will be published. The weak NFP has already raised questions about consumer demand. If retail sales disappoint, recession concerns would intensify, putting pressure on cyclical components of the index.
Separately, monitor Treasury yields. After the NFP release, the 10-year yield pulled back from recent highs but remains near 5.20%–5.30%, levels not seen since 2007. If yields continue to fall, that will support highly liquid stocks in the DJIA.
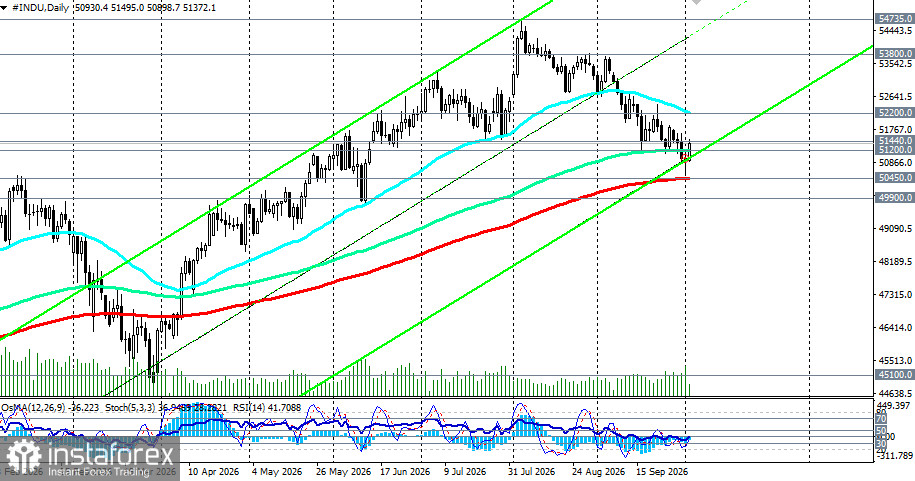
The index bounced from the 50,450.0–50,550.0 zone, which now serves as medium-term support. Confirmation of a trend reversal requires a sustained breakout above 51,500.0 and consolidation there.
InstaTrade aggregated technical analysis (on the 1-hour chart) signals "Strong Buy": 20 of 23 applied indicators favor long positions.
Key levels:
DJIA got a breather after a weak NFP, but the resilience of the bounce is uncertain. The key level for bulls is 51,500.0; for bears, it is 50,900.0.
For short-term traders:
For medium-term investors:
Risk management:
*This overview was prepared using public sources and media reports and represents a price action analysis that depends on many factors; risk management and position monitoring are therefore essential


